Which risks to pass into the price, which market signals to watch and how customer value guides whom to grow with.
Interview summary
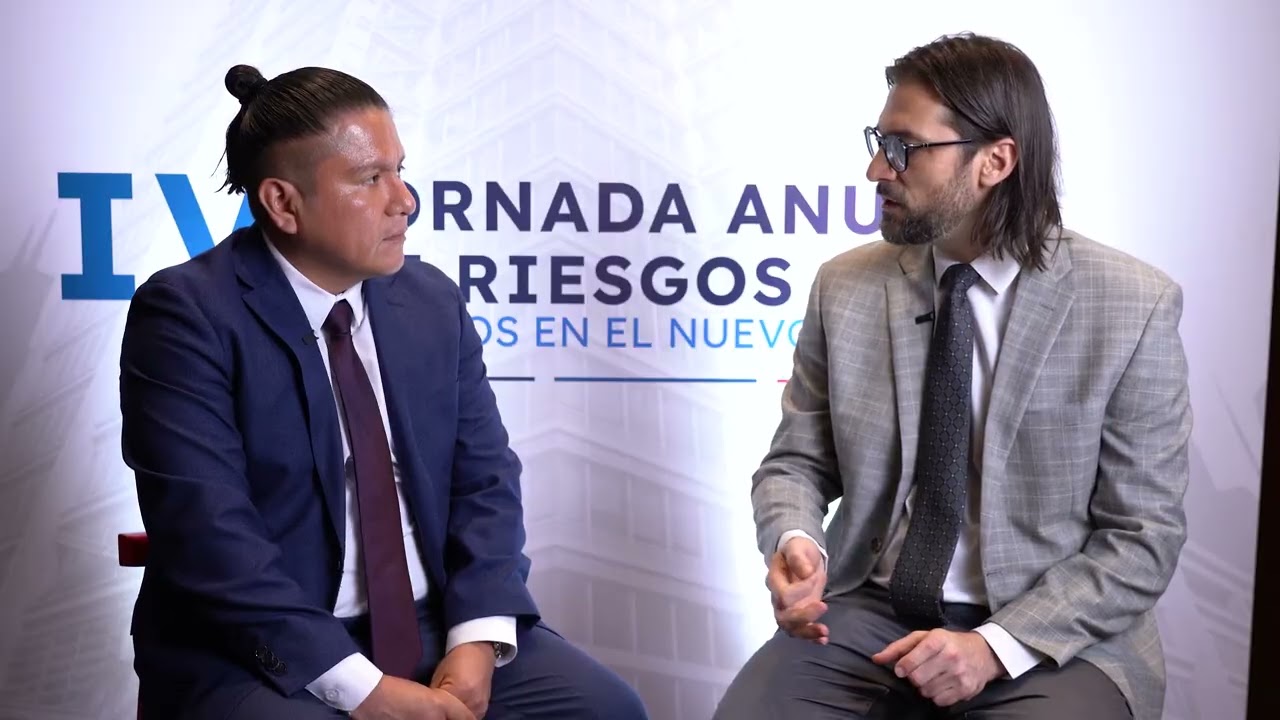
Daniela León Cornejo, founder and CEO of Value of Insights, warns that not every risk can be passed into the price. You have to start by understanding the expected risk of each transaction, such as non-payment or the cost of funds, and put a price on it; creating across-the-board price cushions for a risk whose origin is unknown is a mistake. The risk must be tied to the sectors or segments it will really affect. She also reminds us that a credit offer is not independent of the customer response: raising prices can create adverse selection and lowering them can attract more customers.
Among the market signals to watch she lists conversion, early delinquency, premature charge-offs and changes in payment behavior. To create value with risk-based price optimization she proposes estimating expected revenue over time, with prepayments, cancellations and risk, in customer lifetime value (CLV) models, and asking what can be done to make that value grow: select risk better and build longer-term relationships. This leads to decisions, sometimes uncomfortable ones, about whom to grow with, whom to stay with and which segments to leave.
Topics covered
- Which risks can be passed into the price and which cannot
- Across-the-board price cushions as a mistake
- Customer response and adverse selection
- Market signals: conversion, early delinquency and premature charge-offs
- Customer lifetime value (CLV), prepayments and cancellations
- Deciding which customers and segments to grow with
About Daniela León Cornejo
Expert in pricing and revenue growth, with over 18 years designing monetization strategies in banking, aviation, hospitality, education and manufacturing. She was Director of Pricing and Analytics at Banco de Crédito del Perú (BCP), drove the Credicorp Revenue Management and Pricing Center of Excellence and created the Revenue Management Congress. She holds Executive MBAs from the Kellogg School of Management and the Universidad Adolfo Ibáñez.
More Ries-GO interviews
Credit risk
Credit risk in reserves: anticipating issuer deterioration
Andrés Granados RuizDeputy Director of Financial Risk, Fondo Latinoamericano de Reservas (FLAR)
Market risk and valuation
Beyond VaR: entropic measures for extreme risk
Dany CajasIndependent consultant and creator of Riskfolio-Lib

Looking for an event on a specific topic?
Tell us which topics you would like to take part in at these events by writing to our email info@gestionderiesgo.org
Menu
Sobre Nosotros
CGR Educa
Policies

© COPYRIGHT 2022 ALL RIGHTS RESERVED GESTION DE RIESGO RD SRL.
Connect with our networks